Friends Don’t Let Friends Wear Dow Hats
/script type=”text/javascript” src=”https://app.getresponse.com/view_webform_v2.js?u=S6bT5&webforms_id=A25R”>
Originally posted by Quoth the Raven on his substack:
At some point, probably sooner than most people think, the Dow Jones Industrial Average is going to hit 100,000. And when it does, you can already picture the scene. It’ll be like every major milestone the Dow has ever hit so far combined.
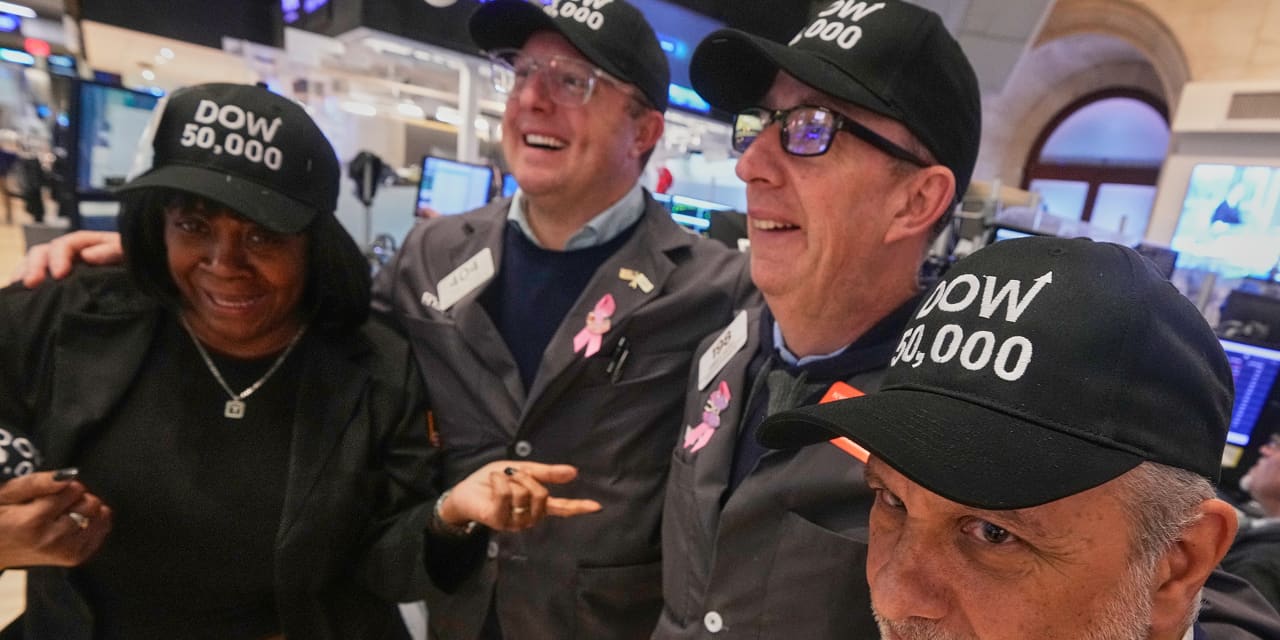
CNBC will run a countdown. There will be breathless retrospectives about how far the market has come. Somebody will dig up footage from the New York Stock Exchange. And, almost certainly, we will print a stupid hat that says “DOW 100,000”.
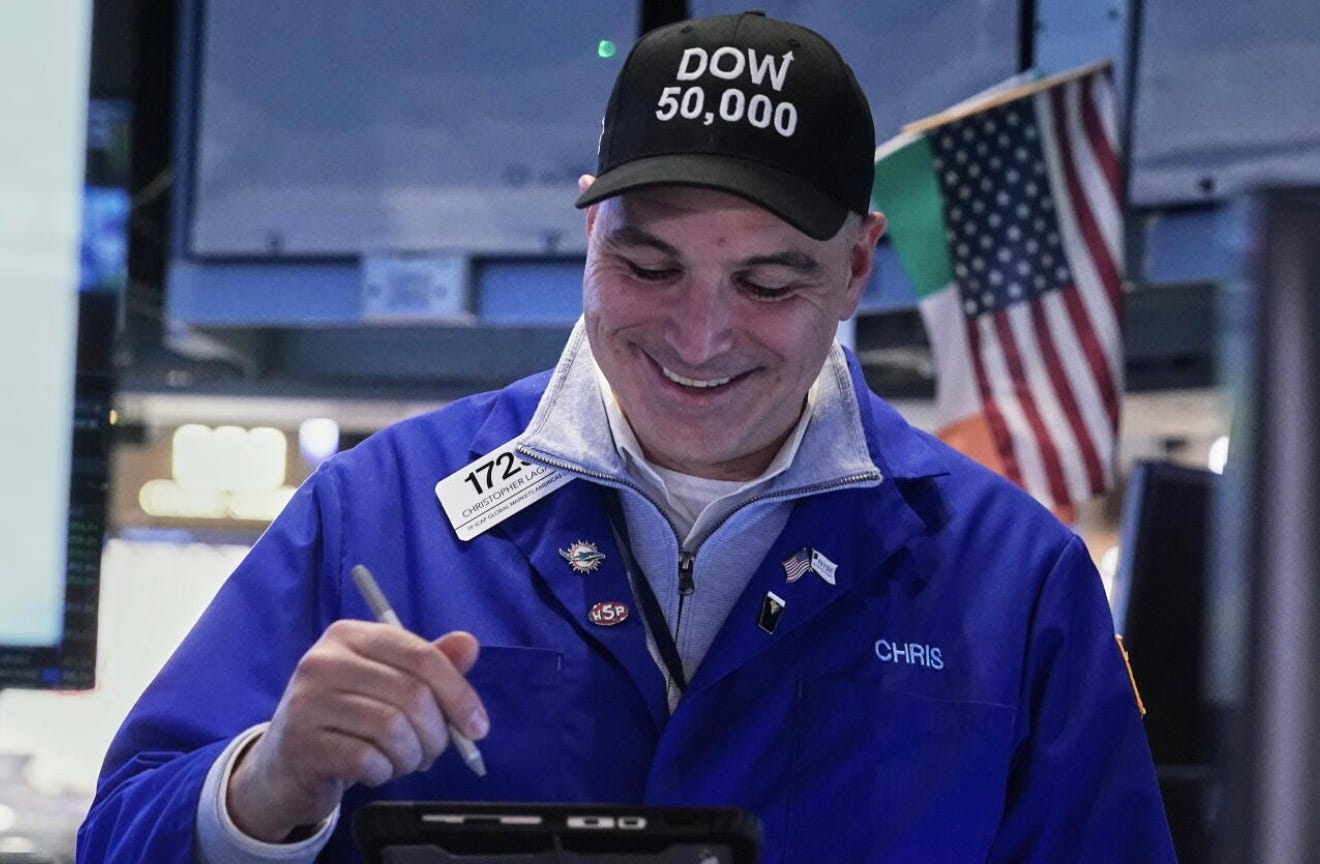
Wall Street has been doing this for decades. One of the great traditions of the old NYSE floor was celebrating big round Dow numbers as though humanity had just split the atom for the first time. When the Dow first crossed 10,000 in March 1999, traders cheered, confetti flew and “Dow 10,000” baseball caps were tossed onto the floor.
And back then, maybe the hats actually made sense. The enormous advance in American equities over the preceding generations represented, to a meaningful degree, an extraordinary expansion in American productive capacity, corporate earnings, technological progress and real wealth creation. The country built things, invented things, became more productive and produced companies that generated vastly more earnings than their predecessors. Obviously monetary inflation existed then too, but there was something tangible underneath the milestone worth celebrating.
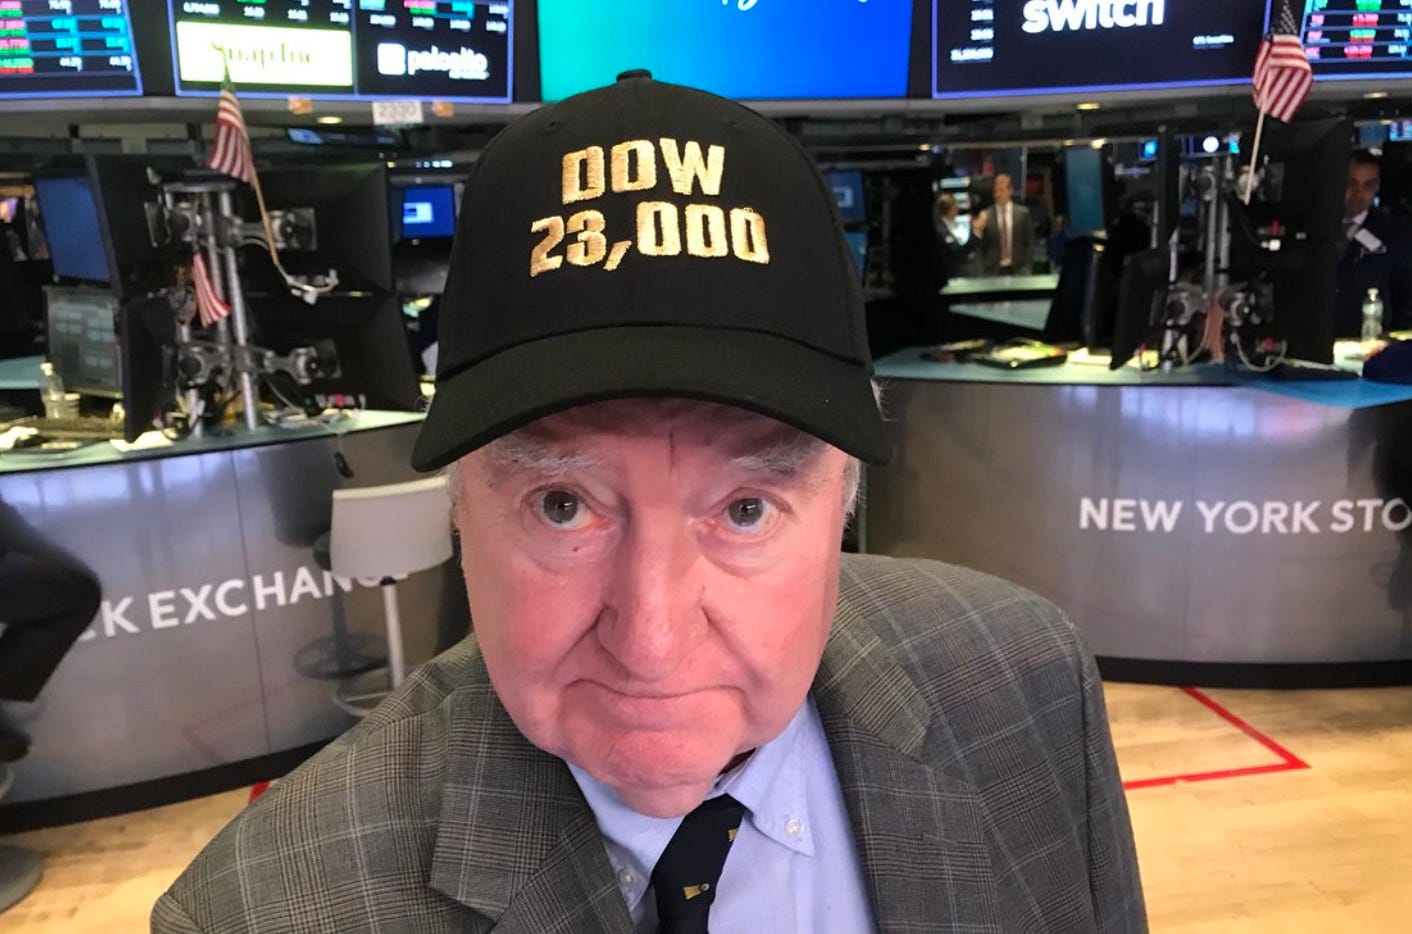
The hats became part of Wall Street folklore, particularly through Art Cashin, the legendary floor trader who bought his NYSE seat in 1964 and spent six decades becoming one of the most recognizable people on the exchange. When the Dow climbed back above 10,000 in October 2009, the hats came back out and Cashin put his rally cap on again. Shortly thereafter, he was donning a hat again at the 20,000 milestone.
And I’m sure more hats will make their way onto the floor when the Dow hits 100,000, which at this rate feels like it could happen before the turn of the decade. But instead of celebrating, we should remember: this number is nominal. And the further we travel into the modern fiat era, the less impressed I am by nominal milestones.
Creating another semiconductor fabrication process takes years of research. Building a factory takes years. Increasing worker productivity is difficult. Growing corporate earnings requires selling something people actually want at a profit. Creating another trillion dollars of nominal purchasing power requires considerably less effort. Those efforts deserve a hat.
That distinction matters because today we increasingly celebrate the scoreboard without asking how much the measuring stick itself has changed. Nominal numbers are wonderful things to celebrate if you don’t ask too many questions about what the unit you’re measuring them in is worth.
If tomorrow we woke up and every stock doubled in dollar terms while every house, gallon of milk, insurance premium, restaurant bill and salary also doubled, would America suddenly be twice as prosperous? Of course not. But hey….hats.
This is the fundamental problem with treating ever higher nominal stock market levels as some kind of national economic scoreboard. Dow 100,000 will absolutely contain genuine economic progress, including productivity, technological advancement, population growth, corporate earnings growth and successful businesses creating real value. I don’t dispute that for a second.
But unlike building a factory, inventing a new technology or doubling the productive output of a business, increasing the number of dollars in the financial system is not some Herculean accomplishment. And when the supply of money and credit expands dramatically over long periods, some of that expansion inevitably finds its way into the nominal prices of scarce and financial assets. Stocks don’t magically sit outside the monetary system.
Inflation raises nominal prices, and stocks are things with nominal prices. Companies eventually sell their products for more dollars, report revenues and earnings in more dollars and own assets valued in more dollars. Investors, meanwhile, value those businesses in those same dollars. Over sufficiently long periods, therefore, asking whether the Dow will reach some enormous nominal number isn’t particularly interesting. Given enough real economic growth, enough inflation and enough time, increasingly absurd nominal numbers become almost inevitable.
The interesting question is how much real prosperity those 100,000 Dow points represent and what those dollars will actually buy when we get there.
For example, when Wall Street first celebrated Dow 10,000 in 1999, the index really was around 10,000; today it sits above 51,000, a nominal gain of roughly 416%. But consumer prices have risen about 103% over the same period, meaning today’s Dow is only around 25,500 when measured in 1999 purchasing power, a real gain of roughly 155%.
Meanwhile, real GDP has grown about 82% and real median household income only about 19%, while M2 money supply has exploded roughly 424%. To be clear, that doesn’t mean the Dow’s rise is simply the product of money printing, as corporate profits have grown enormously too. It does mean that an increasingly large portion of the spectacular number flashing on the screen reflects the fact that we’re measuring stocks in dollars that buy far less than they did when the original Dow 10,000 hats came out.
Celebrating the nominal number without adjusting for the shrinking measuring stick is increasingly like celebrating that your kid grew from four feet to eight feet after you changed the definition of a foot to 6 inches.
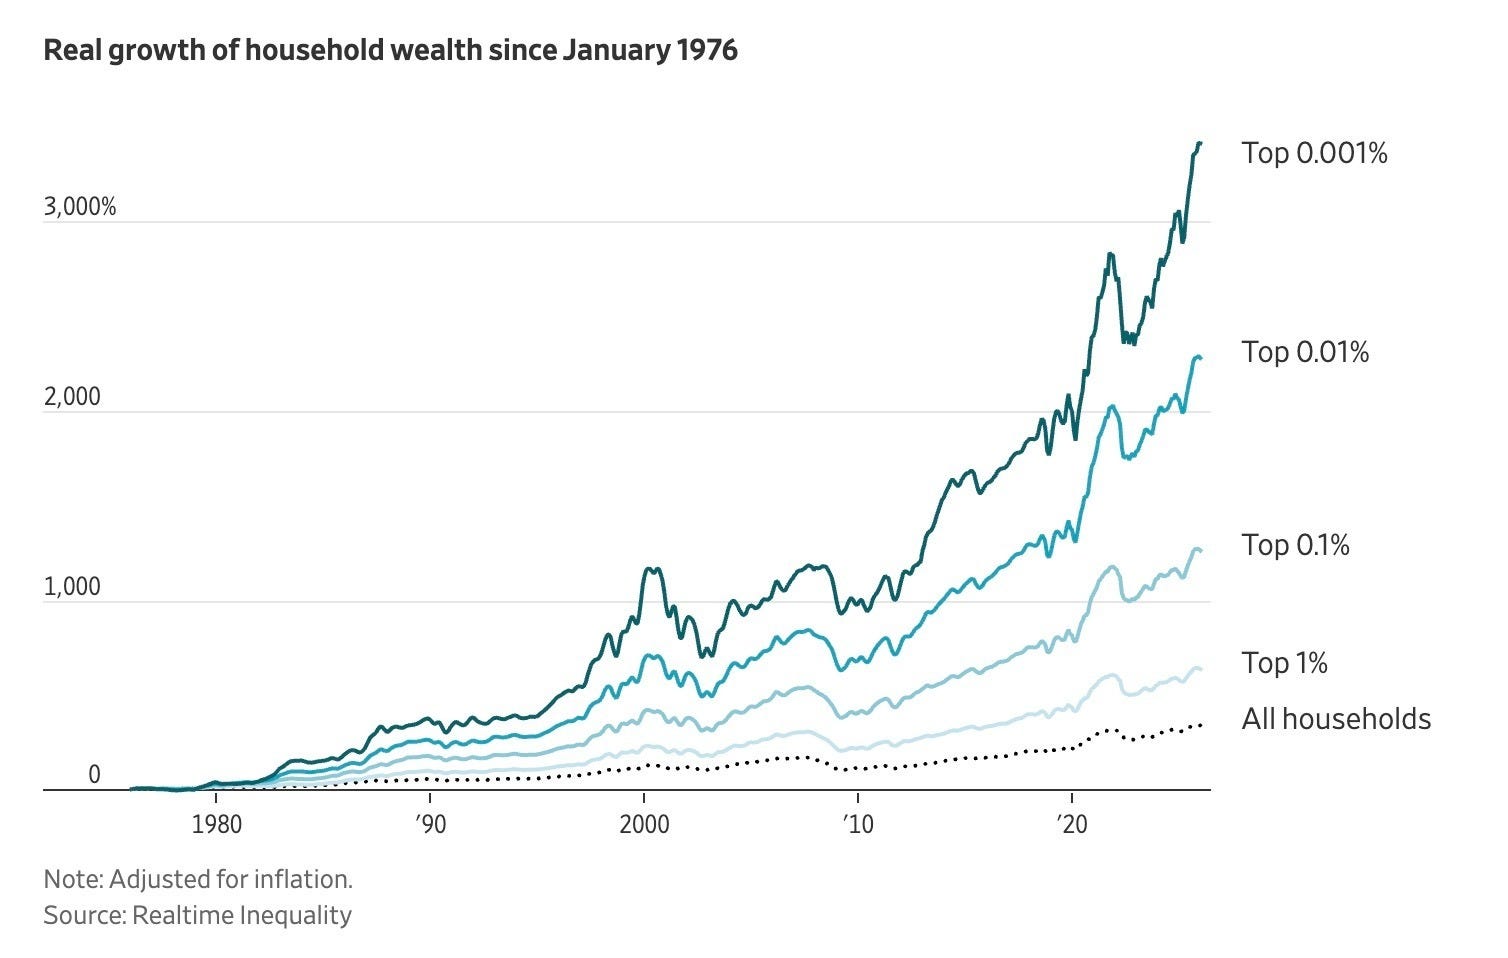
And there’s another uncomfortable part of the celebration. The people receiving most of the benefit from booming financial assets are not distributed remotely evenly across American society.
According to the Federal Reserve’s Distributional Financial Accounts, as of the second quarter of 2026 the wealthiest 10% of American households owned roughly $56.9 trillion of corporate equities and mutual fund shares. The bottom 50% owned about $370 billion. Do the math and the top 10% own roughly 88% of those assets, while the bottom half of the country owns roughly 0.6%.
So when stocks explode higher, who gets rich? Mostly people who were already rich. This isn’t some secret Marxist interpretation of capitalism. It’s literally the Federal Reserve’s own balance sheet data. I’ve written about it often:
The Devil Neither Political Party Will Name
That’s fantastic if you own a shitload of corporate equities. It means considerably less if most of your paycheck disappears into rent, groceries, insurance, utilities, transportation and debt payments before you ever get the opportunity to buy them.
That’s the particularly perverse part of celebrating asset inflation as national prosperity. The people who already own the assets get the protection. The people trying to acquire them get a higher admission price.
That doesn’t mean every stock market gain is caused by inflation. It obviously isn’t. It doesn’t mean monetary policy is solely responsible for wealth inequality, and it doesn’t mean someone becomes poorer every time the Dow rises. The point is simpler: a rising nominal stock index and rising broad based prosperity are two completely different things. Sometimes they coincide. Sometimes a larger portion of the increase is simply the consequence of measuring productive assets in a currency whose supply has grown enormously over time.
The irony is that the monetary and financial architecture that helps produce enormous nominal asset values can create the most spectacular scoreboard precisely for the people who need the scoreboard the least. Asset owners watch their portfolios compound, their homes appreciate, their businesses reprice, their collateral become more valuable and their net worth rise.
Meanwhile, someone without meaningful financial assets can watch the exact same economic process and wonder why a starter home costs a fortune, dinner for two costs $250 and six figures doesn’t feel anything like six figures used to. Both people live in the same economy. Only one of them gets a hat.
So before somebody fires the confetti cannon for Dow 100,000, I’d like to see a few additional statistics displayed next to the giant “100,000” on CNBC. What happened to the purchasing power of the dollar along the way? What happened to median real wages? What happened to housing affordability? How much of the country’s financial wealth is owned by the people wearing the hats, and how much is owned by the people watching them on television?
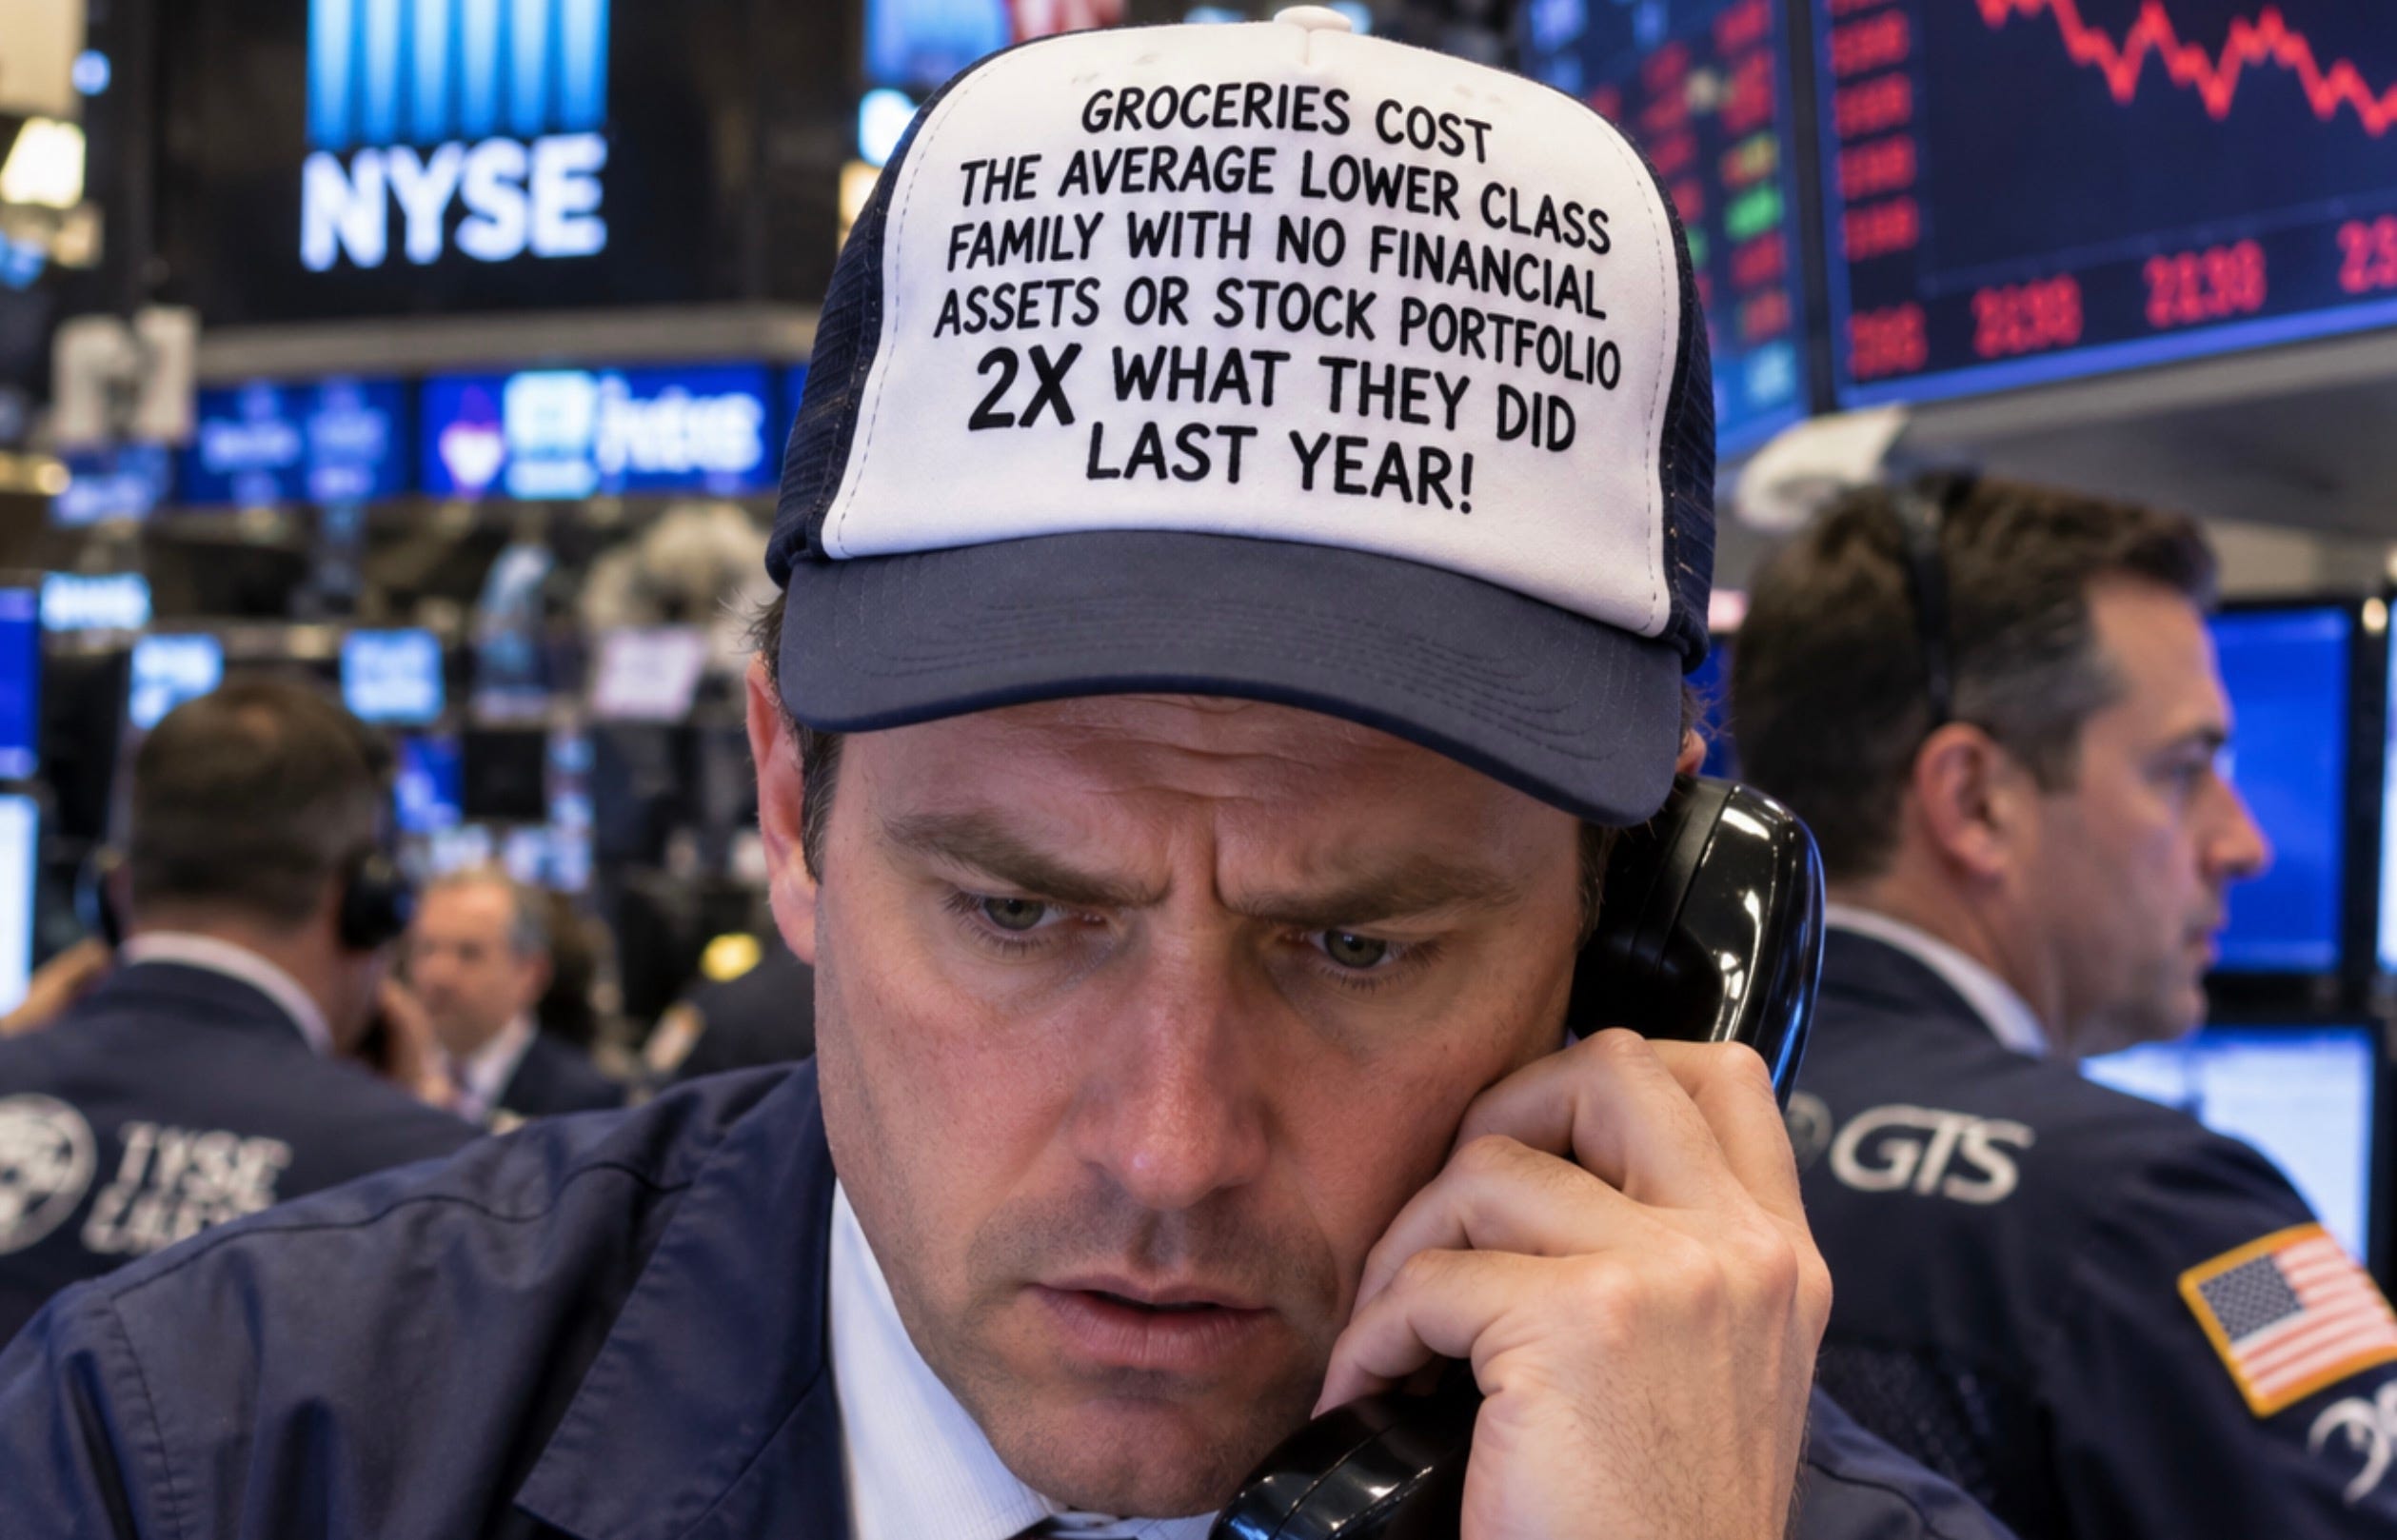
Because “Dow 100,000” fits beautifully across the front of a baseball cap, but “groceries cost the average lower class family with no financial assets or stock portfolio 2x what they did last year!” doesn’t quite fit as well.