Judy Shelton, Scott Bessent And The Coming Gold Revaluation?
/script type=”text/javascript” src=”https://app.getresponse.com/view_webform_v2.js?u=S6bT5&webforms_id=A25R”>
![]()
Originally posted by Quoth the Raven at his substack:
If you were looking for evidence that the United States was seriously considering revaluing its gold reserves, or potentially moving toward some form of gold-linked monetary system, the appointment of Judy Shelton to advise Treasury Secretary Scott Bessent is almost exactly what you would expect to see.
News this morning reports that Shelton, a longtime advocate of monetary reform and former Trump nominee to the Federal Reserve Board, has joined Treasury as a counselor to Bessent. Her responsibilities reportedly include advising on currency policy and evaluating financial conditions in China.
For anybody familiar with Shelton’s views on gold, or the increasingly precarious fiscal position of the United States, I think this deserves considerably more attention than your typical Washington personnel announcement.
Shelton has spent years questioning the monetary system we’ve built since abandoning gold convertibility, advocating for a more stable dollar and proposing ways to bring gold back into government finance.
And now she’s advising the man responsible for managing nearly $40 trillion in federal debt.
About a week ago, I wrote an article exploring what would happen if the United States decided to revalue its enormous gold reserves, which are still officially carried on the government’s books at the absurd price of $42.22 per ounce. I explained how a revaluation could potentially create trillions of dollars in new Treasury financing capacity and, taken to an extreme, fundamentally alter the relationship between the dollar, gold and the national debt.
At the time, it was a thought experiment. One I thought was worth taking seriously, but a thought experiment nonetheless. Now, barely a week later, we have one of the country’s most recognizable proponents of gold-linked monetary reform sitting inside the Treasury Department.
I don’t think that means a gold revaluation is imminent. But I do think it makes the possibility a hell of a lot more interesting. And if you’ve been following my writing about the bond market, the unsustainability of our national debt and the eventual limits of the fiat monetary system, you can probably see why this appointment has my attention.
Shelton hasn’t been subtle about her views. She has proposed issuing 50-year Treasury bonds redeemable in gold at maturity, which she calls Treasury Trust Bonds. Rather than immediately restoring a traditional gold standard, the idea would be to introduce a government security linked to a predetermined quantity of gold, potentially giving investors more confidence in the long-term purchasing power of their investment.
Shelton has argued that investors might accept lower interest rates in exchange for that protection, potentially reducing Treasury borrowing costs. She’s also discussed gold-linked stablecoins and the possibility of other countries issuing similar instruments.
So now we have a Treasury Secretary overseeing a government whose borrowing requirements are becoming increasingly difficult to manage. We have a bond market that I believe is eventually going to force Washington into some very uncomfortable decisions. And now we have a new Treasury adviser who has spent years proposing that the United States use its gold reserves to strengthen confidence in its currency and sovereign debt.
You can call that a coincidence. I have a hard time believing it is.
Shelton’s specific proposal isn’t exactly the same as the gold revaluation mechanism I discussed last week. One involves issuing new debt with a gold redemption feature. The other involves changing the official accounting value of existing gold reserves and potentially monetizing that increase through the Federal Reserve.
But both ideas begin with the same realization: the United States possesses an enormous monetary asset that has been largely absent from the modern dollar system, despite remaining on the government’s balance sheet.
And both suggest that gold could once again become a central part of American monetary policy.
Consider the numbers I laid out last week. The United States holds approximately 261.5 million ounces of gold, yet Treasury continues to value those reserves at just $42.22 per ounce. That leaves the government’s official gold holdings valued at approximately $11 billion, even though their market value is well north of $1 trillion.
At an official valuation of $5,000 per ounce, those reserves would be worth roughly $1.3 trillion. At $10,000, approximately $2.6 trillion. And at an admittedly outrageous $155,000 per ounce, the total would exceed $40 trillion, roughly comparable to the entire national debt.
I’m not predicting $155,000 gold. The point of that extreme example was to illustrate just how powerful the revaluation mechanism could theoretically become.
Treasury already has a system for issuing gold certificates to the Federal Reserve in exchange for credits to its account. If Congress changed the statutory valuation, that mechanism could potentially provide vastly more financing capacity.
Of course, none of this magically creates new wealth. If Treasury actually used trillions of newly created dollars to retire government debt, the consequences could eventually show up in inflation, dollar purchasing power, asset prices and interest rates.
But it would give Washington an entirely different set of financial tools to work with, which is where Shelton’s arrival becomes interesting.
Whether we’re talking about gold-backed Treasury securities, a formal revaluation of America’s reserves or some broader effort to restore gold’s monetary role, the underlying motivation is essentially the same. Washington needs to find ways to restore confidence in its financial obligations without indefinitely relying on expanding debt issuance and Federal Reserve intervention.
I’ve argued repeatedly that the bond market is eventually going to force this issue. The United States cannot assume global investors will absorb unlimited quantities of Treasury debt at politically convenient interest rates forever. At some point, the cost of servicing that debt becomes its own source of financial instability.
And when that happens, policymakers are going to start considering ideas that would have sounded completely ridiculous a decade ago.
Revaluing gold is one of them. Issuing gold-convertible Treasury bonds is another. And introducing some form of gold-linked currency, perhaps through new Treasury instruments or private-sector payment systems, could eventually be another.
A gold-linked bond wouldn’t automatically restore dollar convertibility or establish a new gold standard. But the fact that somebody who has spent years advocating these ideas is now advising the Treasury Secretary should make investors reconsider how far outside the mainstream they really are.
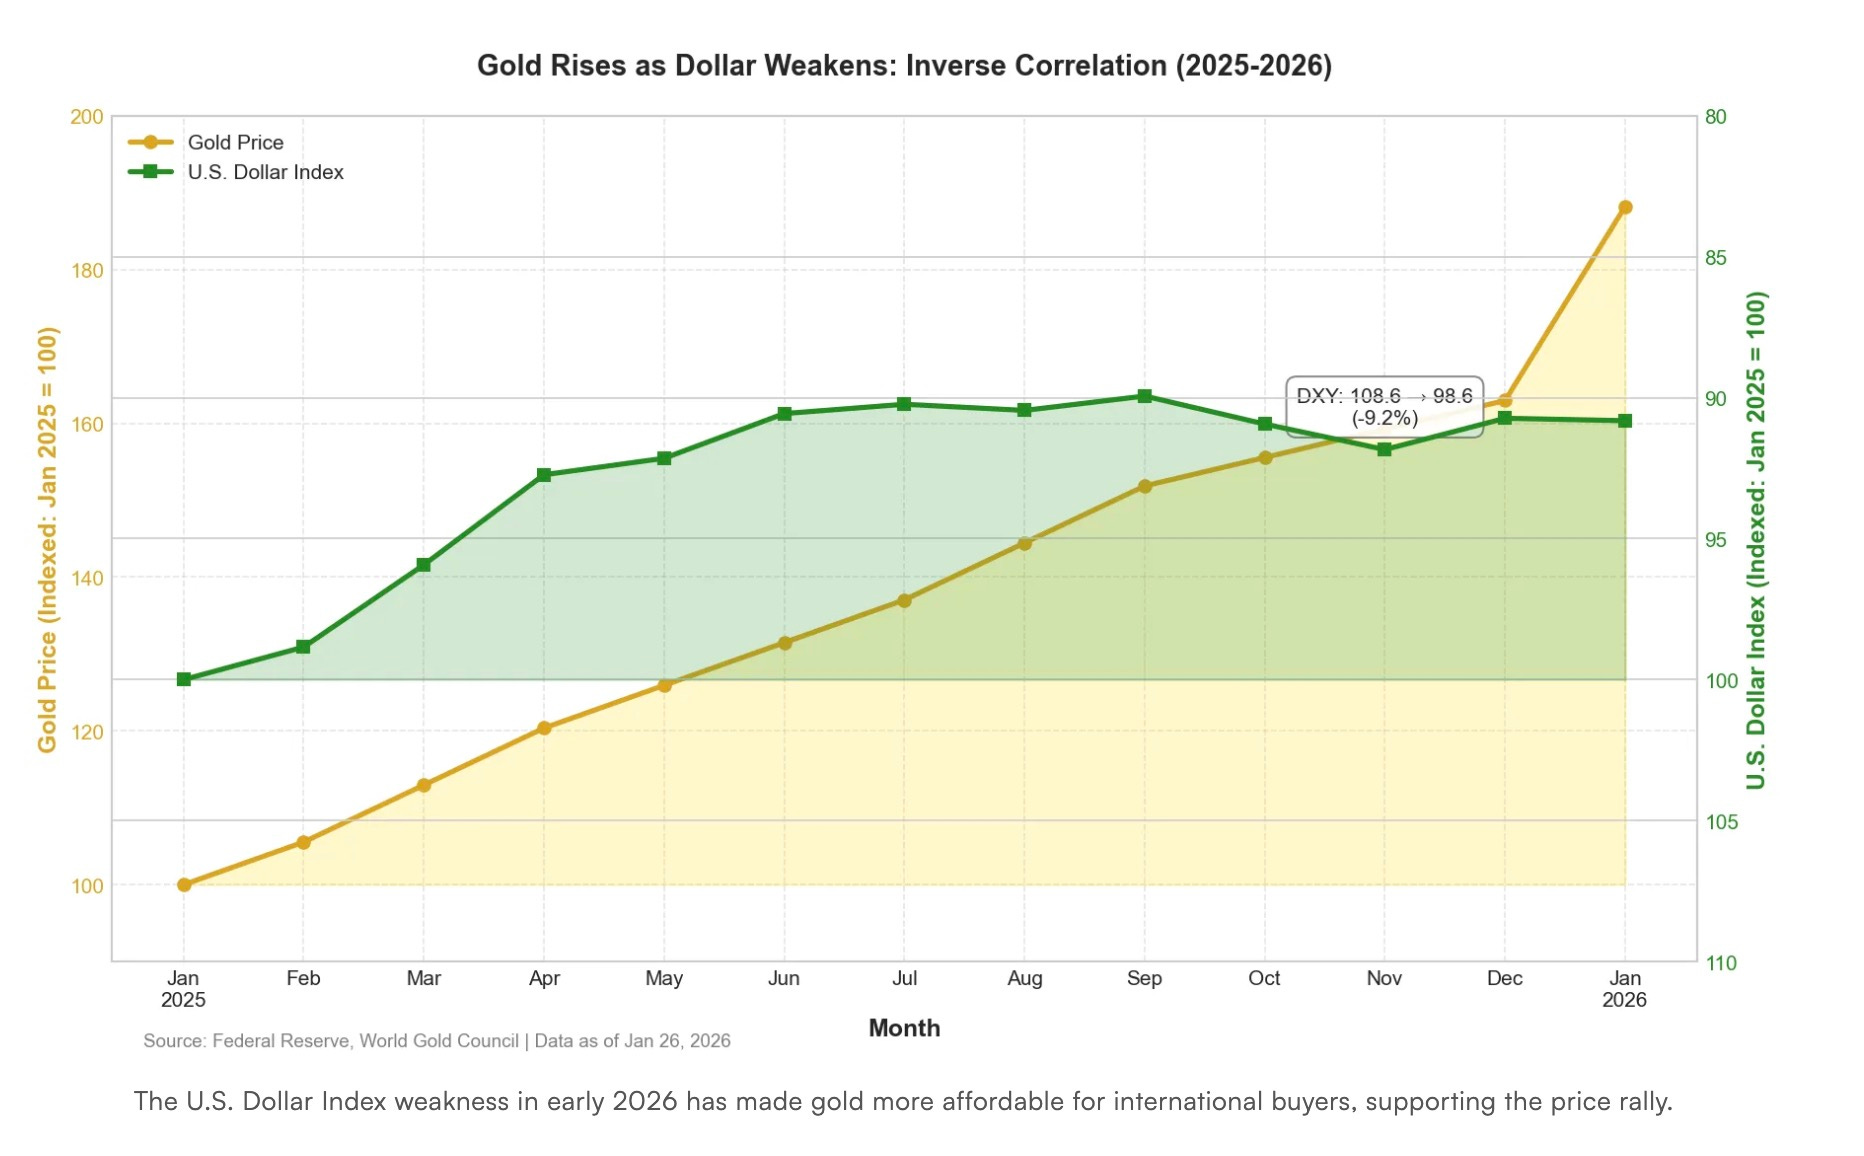
There’s also an international angle here that I find fascinating.
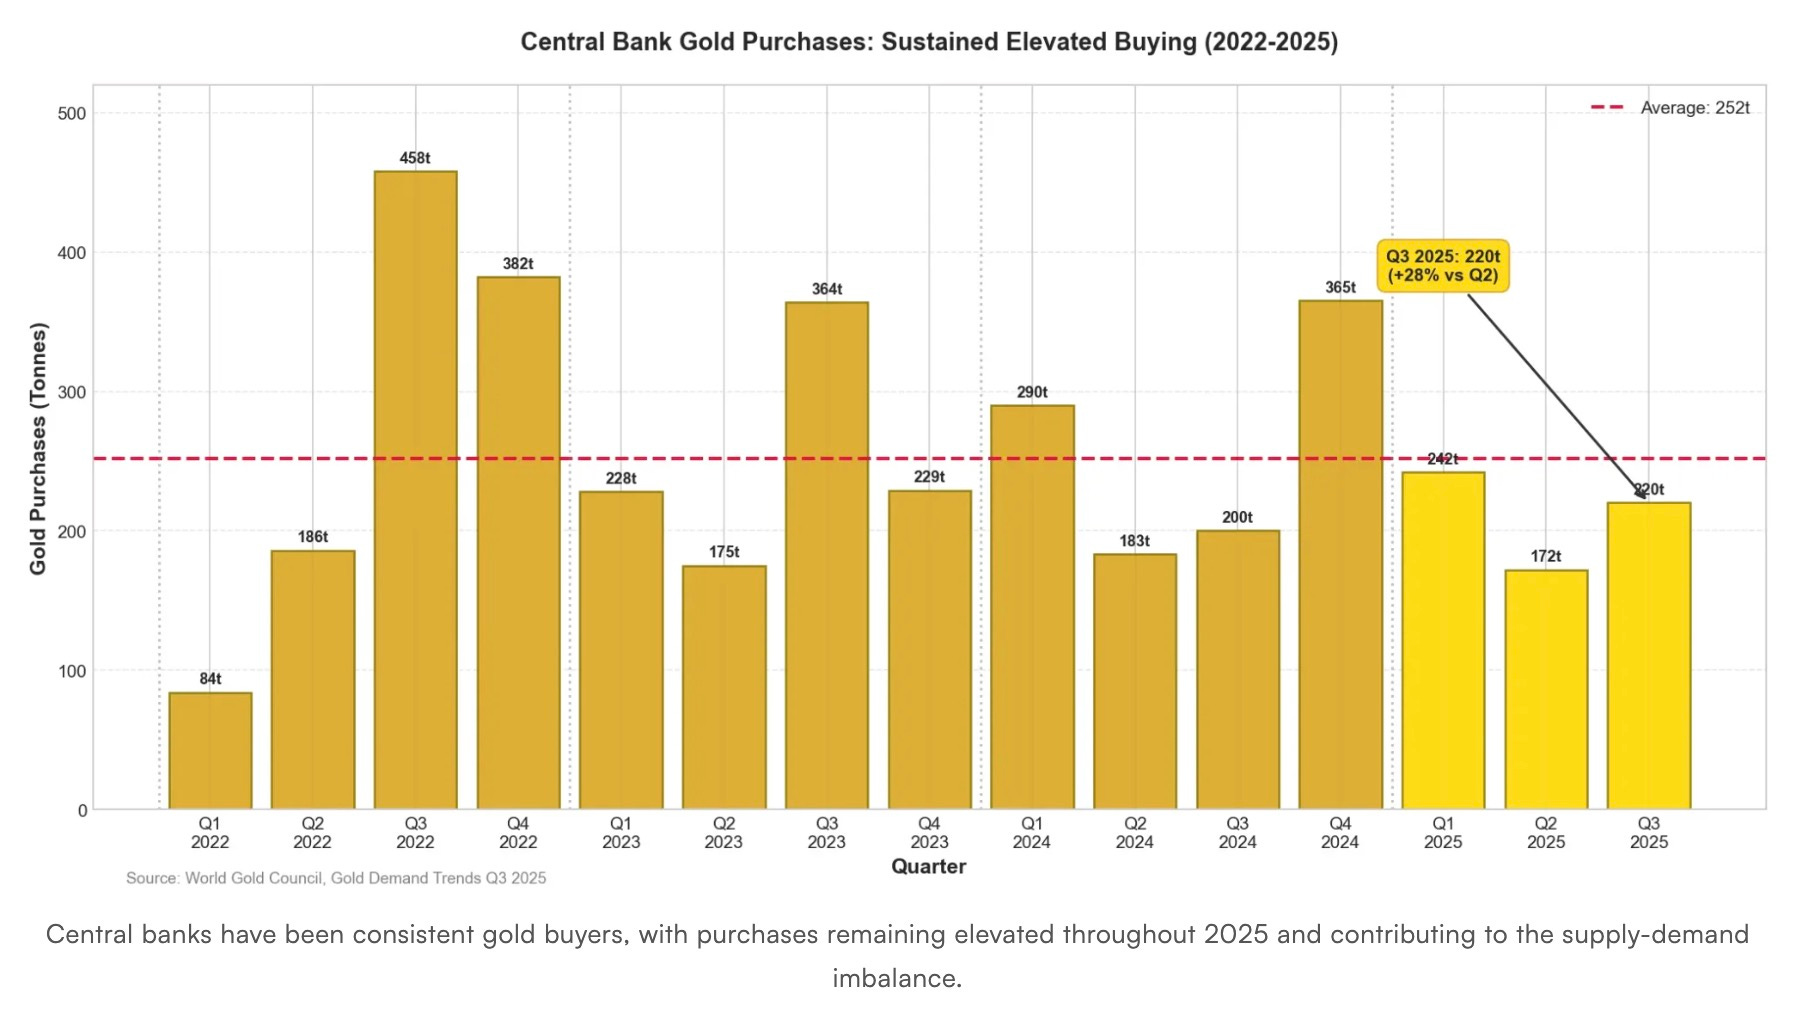
China has continued accumulating gold while competing with the United States for economic and financial influence. Shelton’s reported focus on China is particularly interesting in that context, especially given her previous arguments that America should use its enormous gold holdings to reinforce the dollar’s international standing.
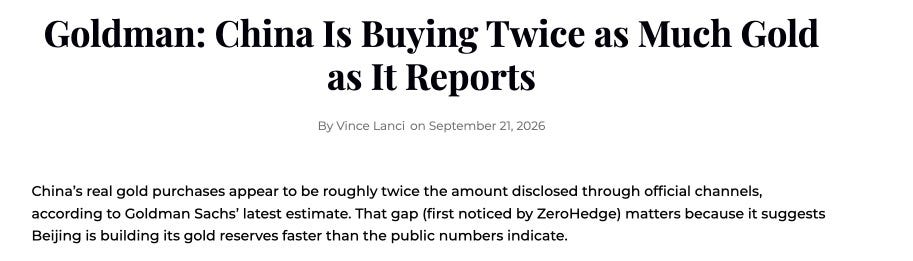
If Washington formally elevated gold’s monetary importance, whether through revaluation, gold-linked debt or some new financial instrument, the implications could extend far beyond the Treasury market.
Central banks and sovereign investors around the world would suddenly have to reconsider the relationship between their gold reserves, their dollar holdings and their exposure to U.S. government debt.
It could represent the beginning of an entirely different conversation about what actually backs the world’s reserve currency.
For decades, the financial establishment has treated gold as a monetary relic, even as central banks continued accumulating it and governments retained enormous reserves. Meanwhile, we’ve built an increasingly leveraged financial system around the assumption that government debt can expand indefinitely and central banks will always be there to manage the consequences.
I’ve never believed that arrangement could last forever. Now, with debt-service costs becoming increasingly burdensome and the bond market showing signs of strain, we may be approaching a period when Washington is forced to confront the limitations of that system.
Shelton’s appointment doesn’t prove a monetary reset is coming. But personnel decisions tell you which ideas policymakers want represented in the room.
And if Treasury were beginning to seriously explore a greater role for gold in the American monetary system, bringing Judy Shelton into the building would make an extraordinary amount of sense.
I suspect the conversation about gold’s role in the dollar system is only beginning.
I wouldn’t be surprised if gold revaluation, gold-linked Treasury securities or some other form of monetary reform eventually becomes a serious policy discussion in Washington. And I think Shelton’s arrival makes that possibility considerably harder to ignore.
—
QTR’s Disclaimer: Please read my full legal disclaimer on my About page here. This post represents my opinions only. In addition, please understand I am an idiot and very often get things wrong and lose money. I may own or transact in any names mentioned in this piece at any time without warning, meaning if I’m long I could sell or if I’m short I could cover at any time. Positions can change immediately. This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning.
I also may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and own things I’m bearish on. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions.
I cannot guarantee the accuracy of any or all facts and figures included in this article though I made an effort to get them right. I have been wrong before and will be wrong again, and encourage you to always double check, do your own research and speak to a licensed financial professional, which I am not.
Contributor posts, guest posts and curated posts have been hand selected by me, but have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author or reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author.
Since 2026, I have been making an attempt to no longer actively trade as much as I once did (read my story here). In an attempt to lead a healthier lifestyle, I’ve also excluded myself from most fantasy sports, sports betting, online and in-person casinos and prediction markets.
My goal is for my investing/saving to be done by recurring contributions mostly to sector ETFs and a few select equities, trusted third parties who oversee my accounts, and advisors. Such advisors or funds, through individual equities, options, index funds, mutual funds, ETFs, or other securities, may have positions in, exposure to, or holdings of names mentioned herein that I know nothing about. Basically, it is possible I could own, have exposure to, or not own anything, at any point.
You are on your own. Do not make decisions based on my blog. I exist on the fringe. Again, I get shit wrong a lot, both in the market and in life, but am trying my best. If you see numbers and calculations of any sort, assume they are wrong and double check them. I failed Algebra in 8th grade and topped off my high school math accolades by getting a D- in remedial Calculus my senior year, before becoming an English major in college so I could bullshit my way through things easier. Hence, I am a writer. I write these posts after a couple beers sometimes. Many times I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour. Thanks, you’ve been a great crowd and don’t forget to tip your servers.