The Hundred Year Family (Part Three): Your Grandchildren Shouldn’t Have to Start From Zero
STAFF NEWS & ANALYSIS
The Hundred Year Family (Part Three): Your Grandchildren Shouldn’t Have to Start From Zero
By
Matt Morgan – September 29, 2026
Matt Morgan – September 29, 2026
/script type=”text/javascript” src=”https://app.getresponse.com/view_webform_v2.js?u=S6bT5&webforms_id=A25R”>
Written by Matt Morgan, Editor at The Daily Bell:
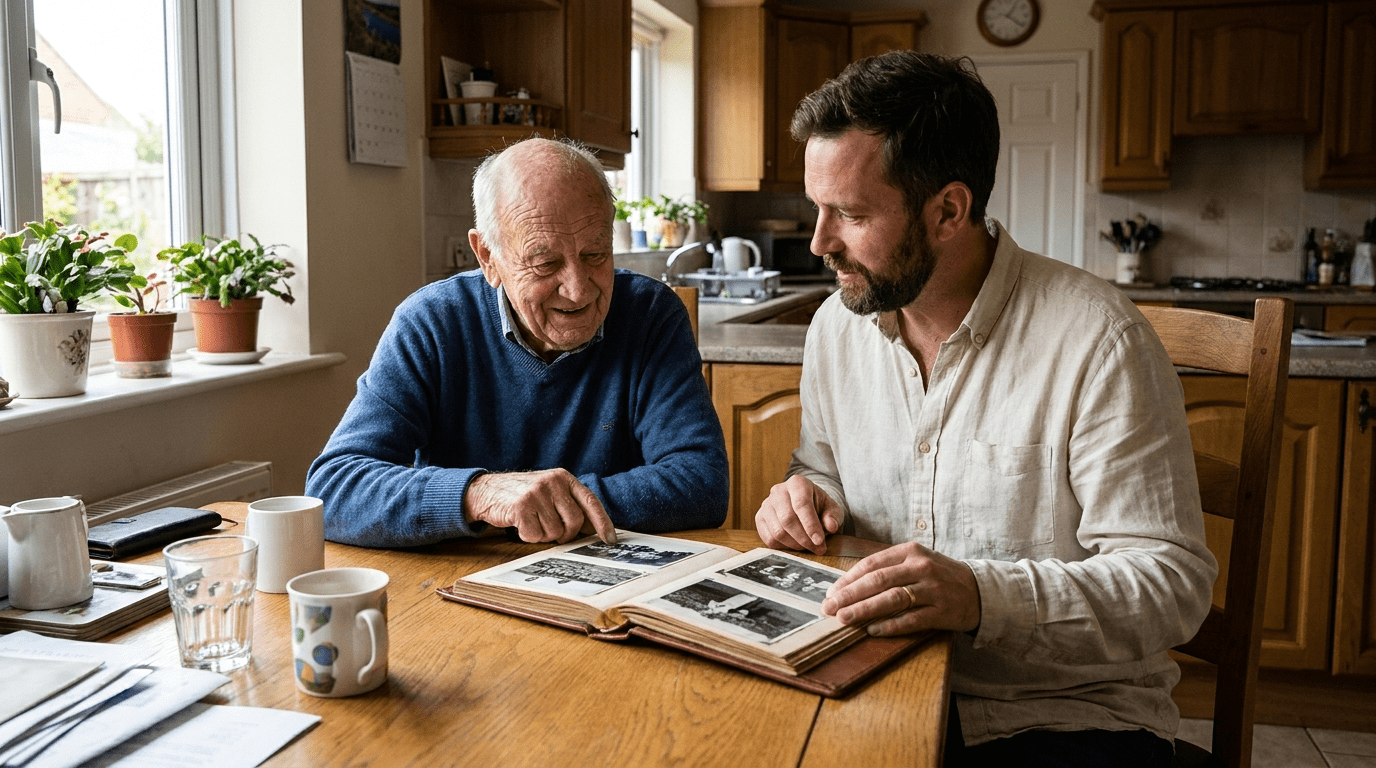
Imagine your grandson signing the lease on his first apartment. He has a job, a small balance in his bank account, and several decisions he has never faced before.
Does he have someone to call who will read the lease with him? Has anyone shown him how to plan for expenses that arrive once a year? Does he know which relatives will give him an honest answer when he makes a mistake?
He’ll have plenty to learn for himself, but some of what he needs could have been passed down long before he picked up the keys. Coming to a resolution on what your grandchildren should be able to count on is a useful place to begin a hundred-year family plan.
In the upcoming release of The Hundred Year Family, Matt Morgan describes two family ledgers. One ledger records financial assets. The other record of account tracks capability: what family members know, how they make decisions, and the responsibilities they have learned to carry.
Money belongs in the plan. Savings can give a young adult breathing room, and a home can provide stability. But the person receiving those advantages needs practice managing them.
Consider what happens when a parent pays every bill without ever explaining one. The children benefit from the money, but they may leave home with little understanding of what their life costs. As a result, years of careful household management remain locked in the parent’s head.
You can start changing that with an ordinary conversation. Explain why you postponed a purchase. Show an older child how you compare the full cost of two options. Let them manage a modest budget and live with a disappointing choice while the consequences are still small.
Those lessons take time, years, most likely a decade or more… It’s just not the same as leaving instructions in a folder, or a will. Those things can’t replace the chance they’ll have to ask questions while you are there.
Every family has knowledge that could disappear when someone dies.
Maybe your mother knows how her parents kept the household going during a long illness. An uncle may remember why a seemingly generous loan damaged a friendship. You may have learned, painfully, how to recognize a promise you should never have trusted.
Ask about those experiences. Write down the details that explain the decision, including what went wrong. What’s neeeded more than a record of flawless ancestors and “self-made” millionaires is an honest account of people who sometimes misjudged things. So, write those down to create your own library of creative, real solutions.
Then give younger family members opportunities to practice. For example, someone learning to organize a family gathering can work within a budget and coordinate help. An older teenager can arrange a repair, ask for a price, and check whether the work was completed. The more these ideas are communicated and implemented, the more children and teenagers will reach out to adults they can trust. A grandchild who knows an aunt well enough to ask an awkward question has access to experience that a list of phone numbers can’t provide.
If you have the desire to transfer freedom and family wealth over more than a hundred years it will reach beyond what anyone you can direct. Your children will make choices you wouldn’t make. Your grandchildren will face circumstances you can’t predict.
Bring your family into the conversation while the plan is still taking shape. Ask what helped them get established and what they wish someone had taught them. Find out what they are willing to teach or take responsibility for themselves. Their participation is another learning opportunity. Your plan has a better chance of continuing when the next generation understands its purpose and has helped decide what belongs in it.
If your family is seeking greater independence from the State, this is practical work.
- Knowing how to manage a household
- Having trusted people to consult
- And being able to offer help can expand the choices available when trouble comes.
Begin with One Page
- Write what you hope your descendants will inherit beyond money.
- Name someone willing to teach one of those things, and agree on when to begin.
- Set a date to discuss what is working.
Your grandson may still have to sign his own lease and pay his own rent, but you can help make sure those aren’t the first occasions on which he learns what either involves.
Posted in STAFF NEWS & ANALYSIS